Factory activity grew for a 10th straight month in October, and the Institute for Supply Management's headline index rose to 55.5. The same report puts its Prices Index at 75.2, with no industry reporting cheaper raw materials. The good number and the bad number come from one survey of purchasing managers, and the bad one is the one that reaches store shelves.
What did the new ISM report say?
ISM released its October 2026 Manufacturing PMI report at 10 a.m. Eastern on Monday, Nov. 2. The headline index was 55.5%, up 1.0 point from 54.5% in September. Anything above 50 means the sector is growing, and this was the 10th month in a row above that line.
The detail is mostly solid. New Orders came in at 55.5 and Production jumped 2.3 points to 59.0. Twelve of the 18 manufacturing industries reported growth, and three reported contraction. Outside the report, one data site listed the consensus forecast at 54.6, which would make this a beat, though I only saw that figure secondhand.
Official record
Institute for Supply Management, October 2026 Manufacturing PMI Report, released Nov. 2, 2026 (PDF).
"No industries reported paying decreased prices for raw materials in October."
"The Prices Index reading is still being driven by (1) increases in steel and aluminum prices that impact the entire value chain..." (ISM release text, Prices section)
Did prices come down?
No. The Prices Index fell 2.7 points, from 77.9 in September to 75.2, and a quick read could take that as relief. It is not. The index is a diffusion measure: it counts how many purchasing managers report paying more, the same, or less, and does not measure how much more.
In October, 53.1% of respondents reported higher prices, 44.1% reported no change, and 2.8% reported lower prices. Count the "no change" group at half weight and you get the 75.2 reading. A drop from 77.9 means a slightly smaller share paid more than in September. It does not mean anything got cheaper, and ISM says raw materials prices rose for the 25th straight month. Its own breakeven for the index, tied to the Labor Department's intermediate-materials producer price series, is 52.8.
What does ISM say is pushing costs up?
The release names the drivers directly. Steel and aluminum prices come first. Tariffs on imported goods come second. Higher prices for petroleum-based products tied to the Middle East conflict come third. Sixteen industries reported paying more for raw materials.
The respondent comments are more specific than the index. A primary metals respondent wrote that "Canadian tariffs continue to have a negative impact on steel." A food and beverage manufacturer said diesel rates and the trucker shortage were raising costs beyond the raw materials themselves. ISM also says tariffs came up in 25% of the negative comments and the Iran war in 21%.
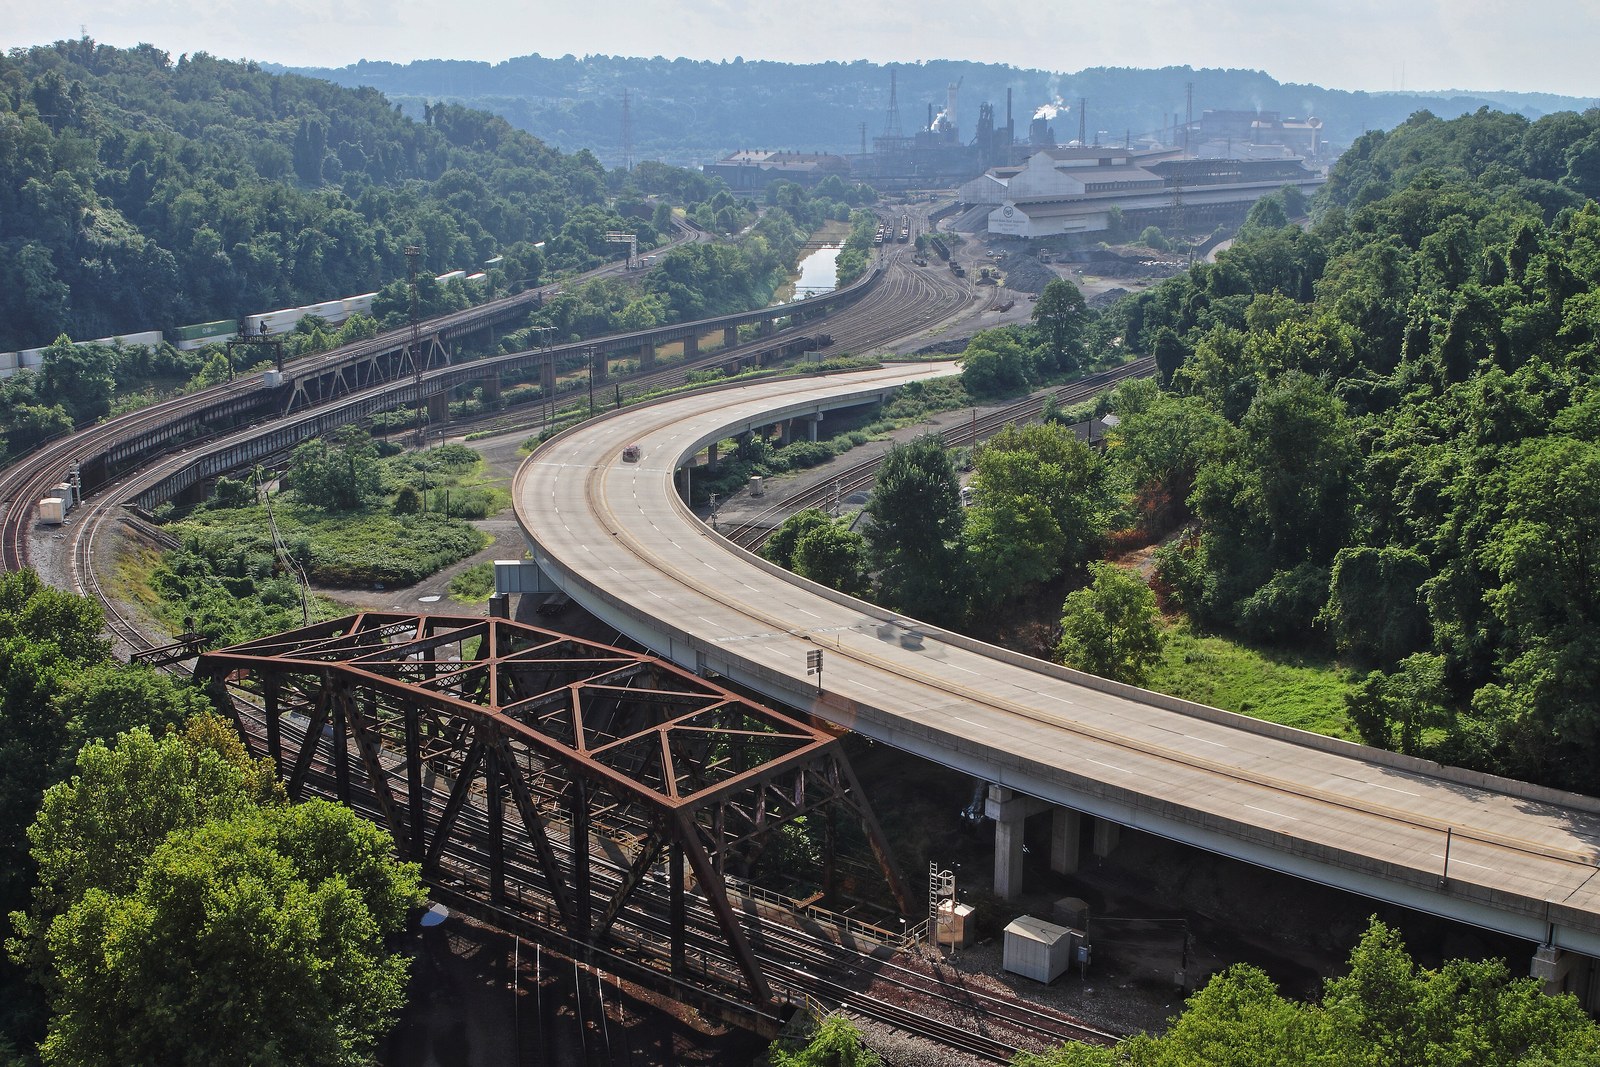
U.S. Steel's Edgar Thomson Works near Braddock, Pennsylvania, seen from above Braddock Avenue and Turtle Creek. Photo: Myrichiehaynes via Wikimedia Commons, CC BY-SA 4.0. Cropped and resized.
Is the hiring picture as strong as the headline?
Not quite. The Employment Index slipped 0.3 point to 52.4, and 74.8% of respondents reported no change in headcount. Only 14.4% reported hiring more, against 10.8% reporting cuts. Eight industries reported employment growth and five reported decreases. ISM's comment tally was 1.8 hiring remarks for every remark about reducing headcount.
That is expansion, but a modest one. A 55.5 headline paired with a 52.4 jobs reading says orders and output are running ahead of hiring. Several respondents also described customers holding back. A fabricated metals respondent said customers were unwilling to commit to anything but the shortest term, and a transportation equipment respondent described a "wait-and-see mode."
What the report does not show
This is a survey of purchasing executives, not a count of invoices. It measures how many firms say they paid more, not how much more, and it is not the Consumer Price Index. The Labor Department's October CPI has not been released, so how much of this cost pressure reaches shoppers is still unmeasured. The attribution to tariffs is also the institute's reading of its panel, not a calculation of how much of the index tariffs explain.
I read the release through the PR Newswire copy and a text extraction of the ISM PDF, and ISM restricts copying, so the quotes above are short. Check the wording against the PDF before repeating any of it. The narrow takeaway holds either way: factories are growing, and by ISM's own count they are still paying more for what they buy.
Header photo: aerial view of U.S. Steel's Gary Works on Lake Michigan in Gary, Indiana. Photo: Grešla via Wikimedia Commons, CC BY-SA 4.0. Cropped and resized.