Initial unemployment claims fell to 196,000 last week, the Labor Department reported Thursday, beating Wall Street's forecast by a wide margin. It is the latest sign 2026 is on pace for its lowest year-to-date average since 1969.
What the Labor Department Actually Reported
Initial claims are simply the count of people filing for unemployment benefits for the first time in a given week, state by state, added up into one national number. It is one of the fastest-moving readings the government produces on the labor market, released every Thursday morning with only a one-week lag, which is exactly why economists watch it so closely for early signs of trouble.
The advance figure for seasonally adjusted initial claims came in at 196,000 for the week ending September 12, a decrease of 10,000 from the prior week's 206,000, according to the Department of Labor's own weekly release. Economists surveyed by FactSet had penciled in roughly 207,500 claims, so the actual number beat expectations by more than 11,000.
The four-week moving average, which smooths out the kind of noise a holiday week like Labor Day can create, dropped to 203,250. That is a decline of 2,750 from the previous week and keeps claims solidly inside the low band they have held for most of the year, according to reporting from U.S. News.
The Insured Unemployment Rate Tells the Same Story
Continuing claims, the running count of people still collecting benefits after an initial filing, fell by 39,000 to 1,730,000 for the week ending September 5. That is the lowest continuing-claims total since January 2024, according to Bloomberg's coverage of the release.
The insured unemployment rate, the share of covered workers actually drawing a check, ticked down to 1.1 percent. That is a genuinely low reading by any recent standard. Employers are not handing out pink slips at scale, and the people who do lose a job are finding their way off benefits fairly quickly.
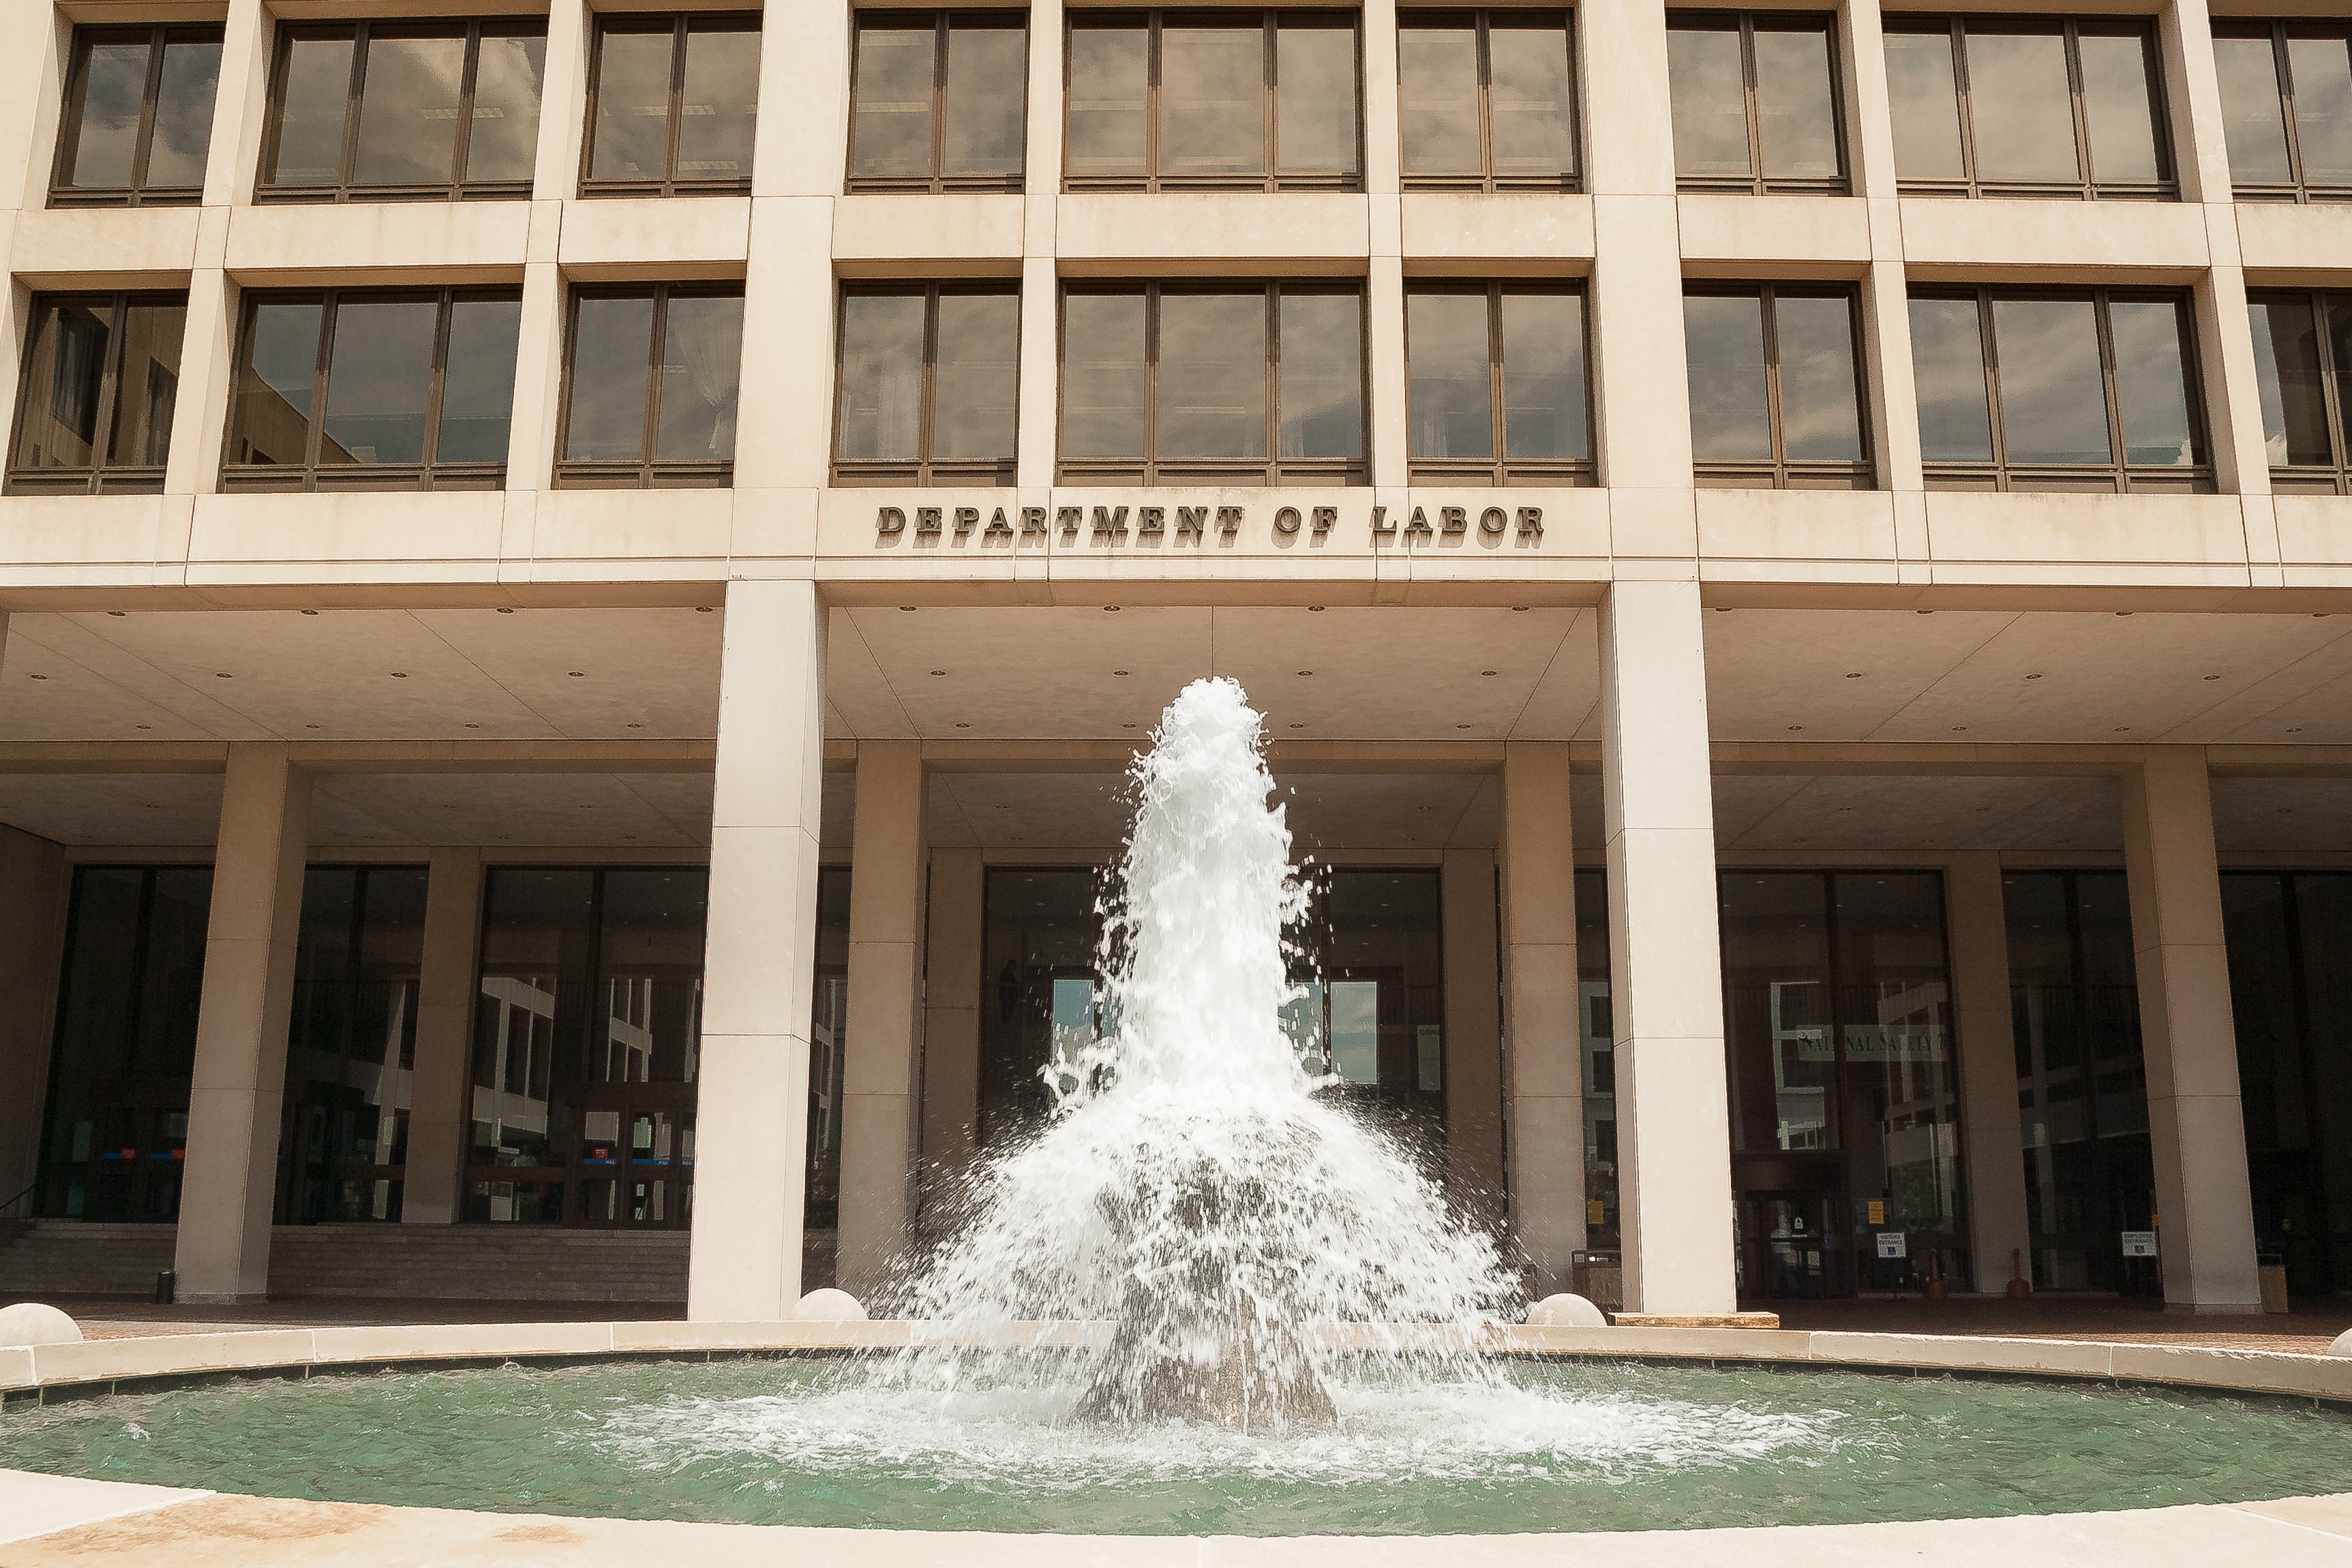
The Frances Perkins Building in Washington, D.C., headquarters of the U.S. Department of Labor. The Employment and Training Administration housed here compiles and releases the weekly unemployment insurance claims report. (U.S. Department of Labor)
Is "Lowest Since 1969" the Full Story?
Several outlets framed this week's number as a callback to the Nixon era, and on the raw count that is technically true. Breitbart's John Carney reported that this year's claims have averaged 210,216 through September, the lowest year-to-date average since 1969 and the third lowest going back to 1967. Prior to this year, a weekly reading this low had only happened four times since 1969.
But a raw headcount comparison across eras skips something important. The U.S. civilian labor force was roughly 169.8 million in August 2026, according to the Bureau of Labor Statistics' own Employment Situation table. Back in 1969, it was closer to 80.7 million. The workforce has more than doubled since the last time claims ran this low on paper, which means 196,000 people filing today represents a smaller slice of the labor pool than 196,000 filers did under Nixon.
None of that makes the number bad news. A labor force twice the size still producing this few claims is, if anything, a stronger signal than the raw comparison suggests. It just means the "last time since 1969" framing, while accurate on the numbers themselves, is a headline shortcut rather than a true apples-to-apples comparison, and readers deserve the fuller picture.
The One Line Buried on Page 8
Reading the actual release rather than just the topline numbers turns up something most coverage skipped. Deep in the state-by-state data, the Labor Department includes a short table of "state supplied comments" for any state with a notable swing in claims. For the week ending September 5, only two states rated a comment at all: California, whose claims rose by 1,967 with "no comment" attached, and Michigan, whose claims rose by 2,075 with a specific explanation on file: "Layoffs in manufacturing industry."
That is the single explicit soft spot the government itself flagged in an otherwise strong report. The release does not say what is driving the Michigan layoffs, and nothing in the data ties it to tariffs, a slowing auto sector, or anything else, so drawing that line would be guessing rather than reporting. What is fair to say is that manufacturing is the one sector the Labor Department's own numbers called out by name this week, in a state that has absorbed real headlines this year, while the national totals kept falling.
The same page cuts the other way for New York, which posted the single largest drop in claims of any state, down 3,790 filings. The state's own comment attributes it to "fewer layoffs in transportation and warehousing, accommodation and food services, and educational services industries." Put the two comments side by side and the honest read is a genuinely mixed, sector-specific picture underneath a strong national headline, not a uniformly rosy one.
An aerial view of the Frances Perkins Building complex. The Bureau of Labor Statistics and the Employment and Training Administration, both headquartered here, are the source of the weekly claims data. (U.S. Department of Labor)
Who Is Actually Losing a Job Right Now
The weekly claims count only shows who is filing for benefits, not why. A separate, broader survey the Bureau of Labor Statistics runs each month gives a fuller picture. In its August 2026 household data, the number of "job losers and people who completed temporary jobs," the closest thing to a true layoff count, fell to 3,245,000, down from 3,309,000 in July and down from 3,447,000 a year earlier.
Meanwhile "job leavers," people who quit on their own terms rather than got pushed out, rose to 914,000 in August from 793,000 in July. Workers walking away from a job by choice, in rising numbers, is generally read as a sign of confidence in finding the next one, not distress. New entrants to the labor force, often recent graduates looking for a first job, actually fell slightly to 702,000 from 761,000, which is the one soft data point in an otherwise reassuring table.
This Isn't the First "Since 1969" Headline This Year
Thursday's number is not an isolated blip. Claims briefly touched even lower levels earlier this year, and outlets covered it in real time. Back in April, RedState wrote up a reading described as "a number not seen since Nixon was president." In July, claims fell again, and the same writer noted the level was "the lowest level since the days of Woodstock."
Axios covered that same July reading and made a point worth repeating: a labor market performing like this should be leading every broadcast. Instead, a genuinely strong print gets a few paragraphs wedged between other stories, then the news cycle moves on until the next one arrives a few weeks later and the whole pattern repeats.
Why This Matters Heading Into the Fed's Next Move
This is the first full week of labor-market data since the Federal Reserve raised its benchmark rate on September 16, its first hike since 2023, bringing the target range to 3.75 to 4 percent. Chairman Kevin Warsh told reporters inflation has been "too high ... for too long" and said this summer's inflation readings did not convince him the underlying trend had meaningfully improved.
A labor market still generating this few layoffs gives the Fed room to keep leaning on rate hikes without worrying it is about to tip the country into a wave of job losses. That cuts two ways for household budgets. It is good news if you are worried about keeping your job. It is a harder pill if you are waiting on mortgage rates or credit card rates to come down, since a Fed that sees full employment has less reason to ease up.
Sixteen of the eighteen Fed officials who submitted projections after the September meeting think at least one more rate increase is coming before the year is out, with four of them penciling in two. A jobs market this resilient is part of why. It gives Warsh and the rest of the committee cover to keep leaning against inflation without the usual political and economic pressure that comes from rising unemployment.
For now, the actual data says the same thing it has said most weeks this year: layoffs remain rare, and whatever else is weighing on family budgets right now, a wave of pink slips is not the driver. That is worth saying plainly, especially in a year when plenty of other headlines suggest otherwise.